As every year, vehicle taxation is updated, and 2022 is no exception.
Here are all the changes fleet managers need to know regarding the new weight-based penalty, the TVS (or NTU), the ecological penalty and bonus, non-deductible depreciation, benefits in kind, and VAT on fuel.
The new weight-based penalty in detail
The weight penalty will be introduced on January 1, 2022, after being voted on in the National Assembly at the end of 2021. A measure which aims to send a signal to "stop this frenzy of heavy vehicles", said Barbara Pompili, the Minister for Ecological Transition.
It concerns all vehicles over 1800 kg, at a rate of €10 per kilo above 1800 kg, with the exception of electric or hydrogen vehicles and plug-in hybrid vehicles whose all-electric urban driving range is at least 50 km.
Note that the total penalty (CO2 penalty + weight penalty) cannot exceed the maximum penalty scale (€40,000 before application of VAT).
Company car tax and new usage taxes
In 2022, the Company Car Tax (TVS) will be replaced by two New Usage Taxes (NTU) :
- Annual tax on CO2 emissions : operation and scale identical to the 'CO2 Tax' in force in 2021
- Annual tax on air pollutants : operation and scale identical to the 'Air Tax' in force in 2021
How to calculate the TVS (Tax on Company Vehicles) in 2022?
The rates communicated for the first component, the CO2 Emissions Tax, are still based on the CO2 emission rate, as before, and correspond to a full year of use.
The calculation method differs, however, depending on whether the vehicles were registered before or after March 1, 2020 (NEDC vs WLTP).
For vehicles using NEDC (registered up to February 29, 2020): the scale remains unchanged since 2019
For vehicles registered after March 1, 2020: a tax based on WLTP CO² is applied (lower since 2021 for the least polluting vehicles (up to and including 157g) = unchanged since 2021
The minimum duration of 30 consecutive days of use to be eligible for NTU is retained.
NEW :
The calculation based on the number of quarters is abandoned in favor of the actual (calendar) number of days of ownership or use.
NB: the declaration of NTUs in January 2023 for the year 2022 can still, and for the last time, be made on the basis of quarters of use.
Ecological bonus 2022
The bonus in effect since July 1, 2021 is extended by 6 months, making it valid until June 30, 2022 (decree 2021-1866 published on 12/29/2021).
Effective July 1, 2022 :
- The bonus is reduced by €1000 for all eligible vehicles.
- The bonus for PHEVs (plug-in hybrid vehicles) is disappearing.
Here is a summary table of the 2022 bonus and its evolution throughout the year.
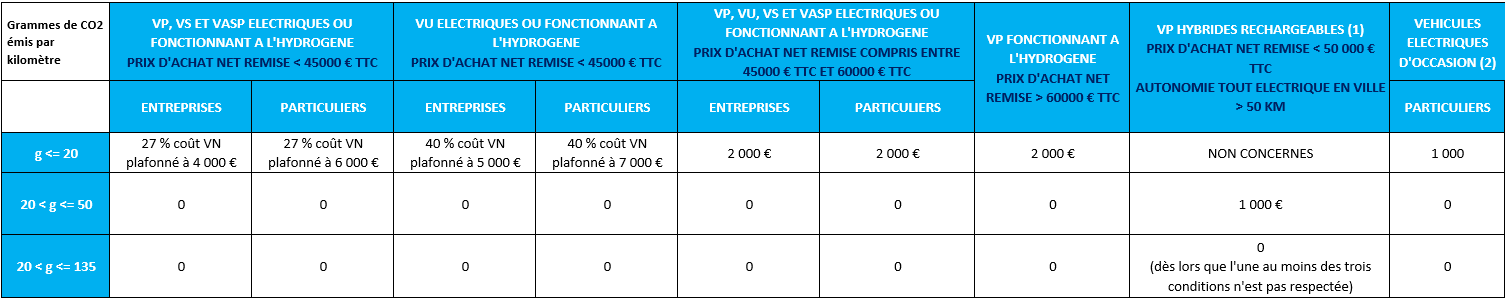
ECOLOGICAL BONUS FOR THE PERIOD FROM 26/07/2021 TO 30/06/2022
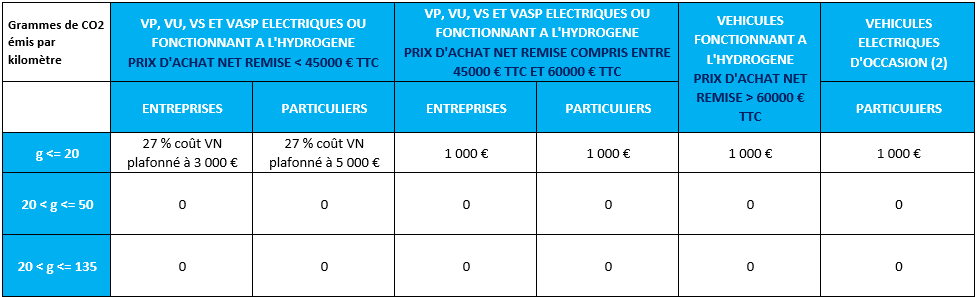
ECOLOGICAL BONUS FOR THE PERIOD FROM 01/07/2022 TO 31/12/2022
(1) To be eligible for the bonus, plug-in hybrid vehicles must comply with the following three conditions: CO2 emission rate between 21 and 50 g, discounted net purchase price less than or equal to €50,000 including VAT, all-electric driving range in the city strictly greater than 50 km
(2) To be eligible for the bonus, used electric vehicles must have been registered for at least 2 years.
Stricter environmental penalty in 2022
The 'CO2' ecological penalty is becoming even stricter in 2022, since it:
- It starts at 128g of CO2 (compared to 133g in 2021)
- This can amount to €40,000 (as a reminder, the maximum penalty was €30,000 in 2021)
However, a new rule has been introduced: the penalty cannot exceed 50% of the vehicle's purchase price. As with the calculation of the bonus eligibility price, only immediate discounts are taken into account.
| 2020 | 2021 | 2022 | 2023 | |
|---|---|---|---|---|
| CO2 levels in g/km | 138 g CO² | 133 g CO² | 128 g CO2 | 123 g CO² |
| Maximum penalty* | 20 000 € | 30 000 € | 40 000 € | 50 000 € |
*The CO² penalty cannot exceed 50% of the discounted vehicle price including VAT
The various exemptions for electric and hybrid vehicles
Permanent exemption:
Electric or hydrogen-powered vehicles emitting less than 20g of CO2 are permanently exempt from the two new usage taxes.
vehicles are permanently exempt from the Annual CO2 Emissions Tax provided that:
- Their CO2 emission rate does not exceed 50 g (NEDC) or 60 g (WLTP)
- They do n't run on diesel.
Note: The Annual Tax on Air Pollutants remains due for exempt hybrids.
Temporary exemption:
Temporary exemptions are maintained for 3 years for hybrid vehicles :
- Provided that the CO2 emission rate is between 51 g and 100 g (NEDC) or between 61 and 120 g (WLTP)
- Provided they do n't run on diesel
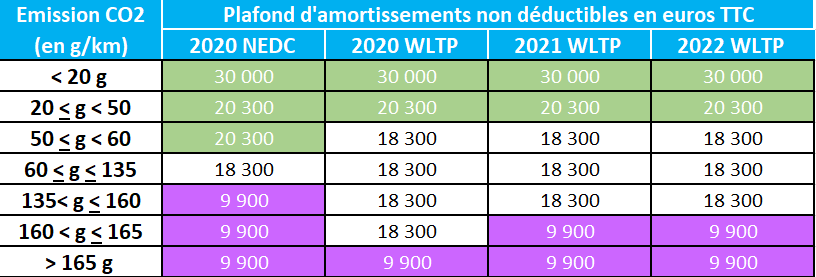
Non-deductible depreciation: the ceiling reached in 2022
The ceiling defined by the 2017 Finance Law has now been reached and is maintained for 2022:
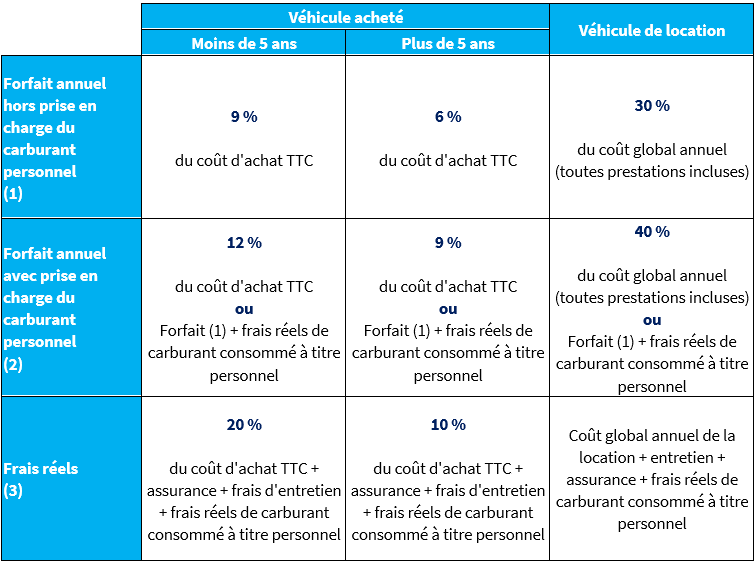
Vehicles in kind benefit
The method for calculating benefits in kind remains the same in 2022.
Electric vehicles still benefit from:
- A 50% reduction on the amount of benefits in kind, up to €1800 per year (€150 per month), until December 31, 2022
- Top-ups covered by the employer do not increase the rate applicable to the amount of benefits in kind
VAT on fuel in 2022
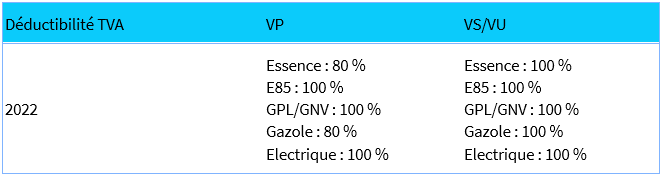
As planned for 2022, the VAT deductibility rate on petrol is now 100% on commercial vehicles (CVs), thus offering the same deductibility for petrol and diesel vehicles.
In 2022, VAT deductibility on petrol and diesel passenger vehicles remains at 80%.
It rises to 100% for vehicles running on E85 superethanol, LPG or CNG, and for electric vehicles.
FATEC Group, experts in fleet management, can advise and support you in managing your fleet and its tax implications.
Learn more